

22-Sep-2026
Every leap in AI now rests on a physical bill: the chips, memory, interconnects, and power packed inside the data center. Against this backdrop, Yole Group releases its latest report, Data Center Semiconductor Trends 2026, offering a comprehensive analysis of the semiconductor market, ecosystem, supply chain, and technologies shaping the data center semiconductor landscape.
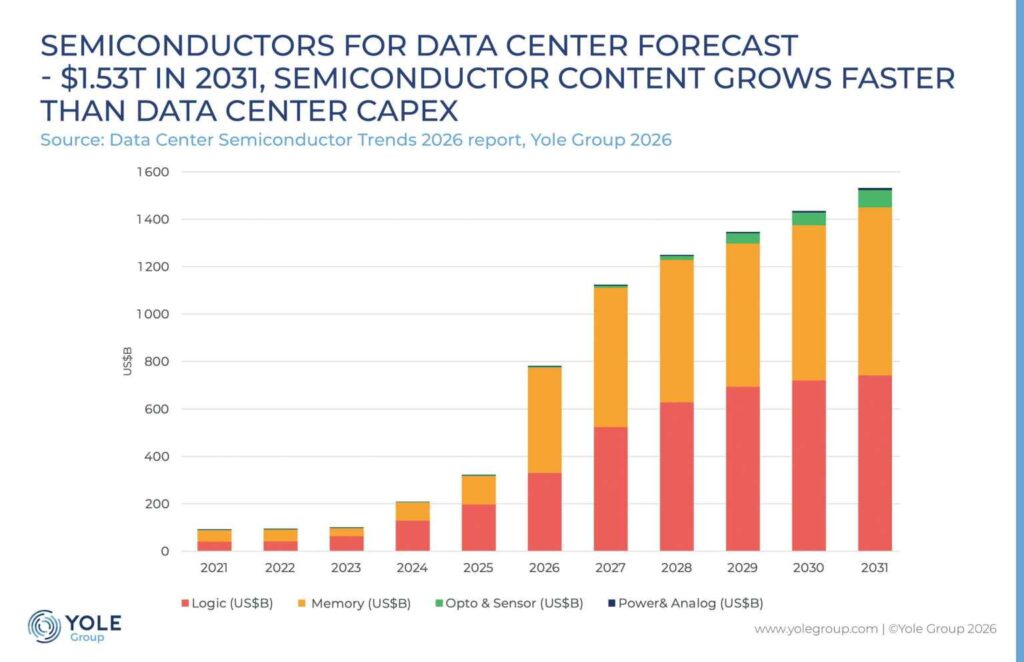
AI has become the semiconductor industry’s single growth engine, and it is compounding faster than any prior cycle. Each Yole Group edition since 2024 has captured a further step change in demand, with the market set to roughly double in 2026 alone. Yole Group’s analysts now size it at $1.5 trillion by 2031, the point at which semiconductor value starts growing faster than the data center capex that drives it, itself heading toward roughly $1.8 trillion by the end of the decade.
Yole Group’s new edition tracks how the semiconductor content of an AI data center is shifting, segment by segment:
Underpinning this is a shift from the chip to the rack. AI performance is now sold at the full-rack level, in systems such as Nvidia’s NVL576, AMD Helios, AWS NL72, and Google Ironwood, and the real bottleneck at scale has become advanced-packaging capacity, alongside a fast-moving HBM roadmap.
Concentration and regionalization are reshaping the supply chain. No single company covers the whole chain, though Nvidia has grown into a supply-chain powerhouse, capturing ~16% of all semiconductor revenue and locking in priority capacity at TSMC, SK hynix, and packaging partners. Regional paths diverge: Europe backs sovereignty with a €200 billion InvestAI plan, the United States is defined by Nvidia’s dominance, and China’s build-out stays gated by SMIC under US export controls.
But power is fast becoming the industry’s real ceiling. With AI racks approaching 1 MW by decade’s end, higher-voltage delivery (800 V, SiC and GaN) and direct liquid cooling are becoming standard, and grid access is now as much a constraint as the chips themselves.
With AI a durable, long-term growth driver, the technology, supply chain, and competitive dynamics behind this market have never mattered more to chipmakers, memory and packaging suppliers, hyperscalers, ODMs, and investors. Data Center Semiconductor Trends 2026 provides the market intelligence and technology insight to navigate it and spot the next opportunities.
For more information about this report or to schedule an interview with Yole Group analysts, please contact us.
Stay connected with Yole Group for more insights!
Source: www.yolegroup.com